Chapter 4: The Ledger My Father Swore Didn't Exist
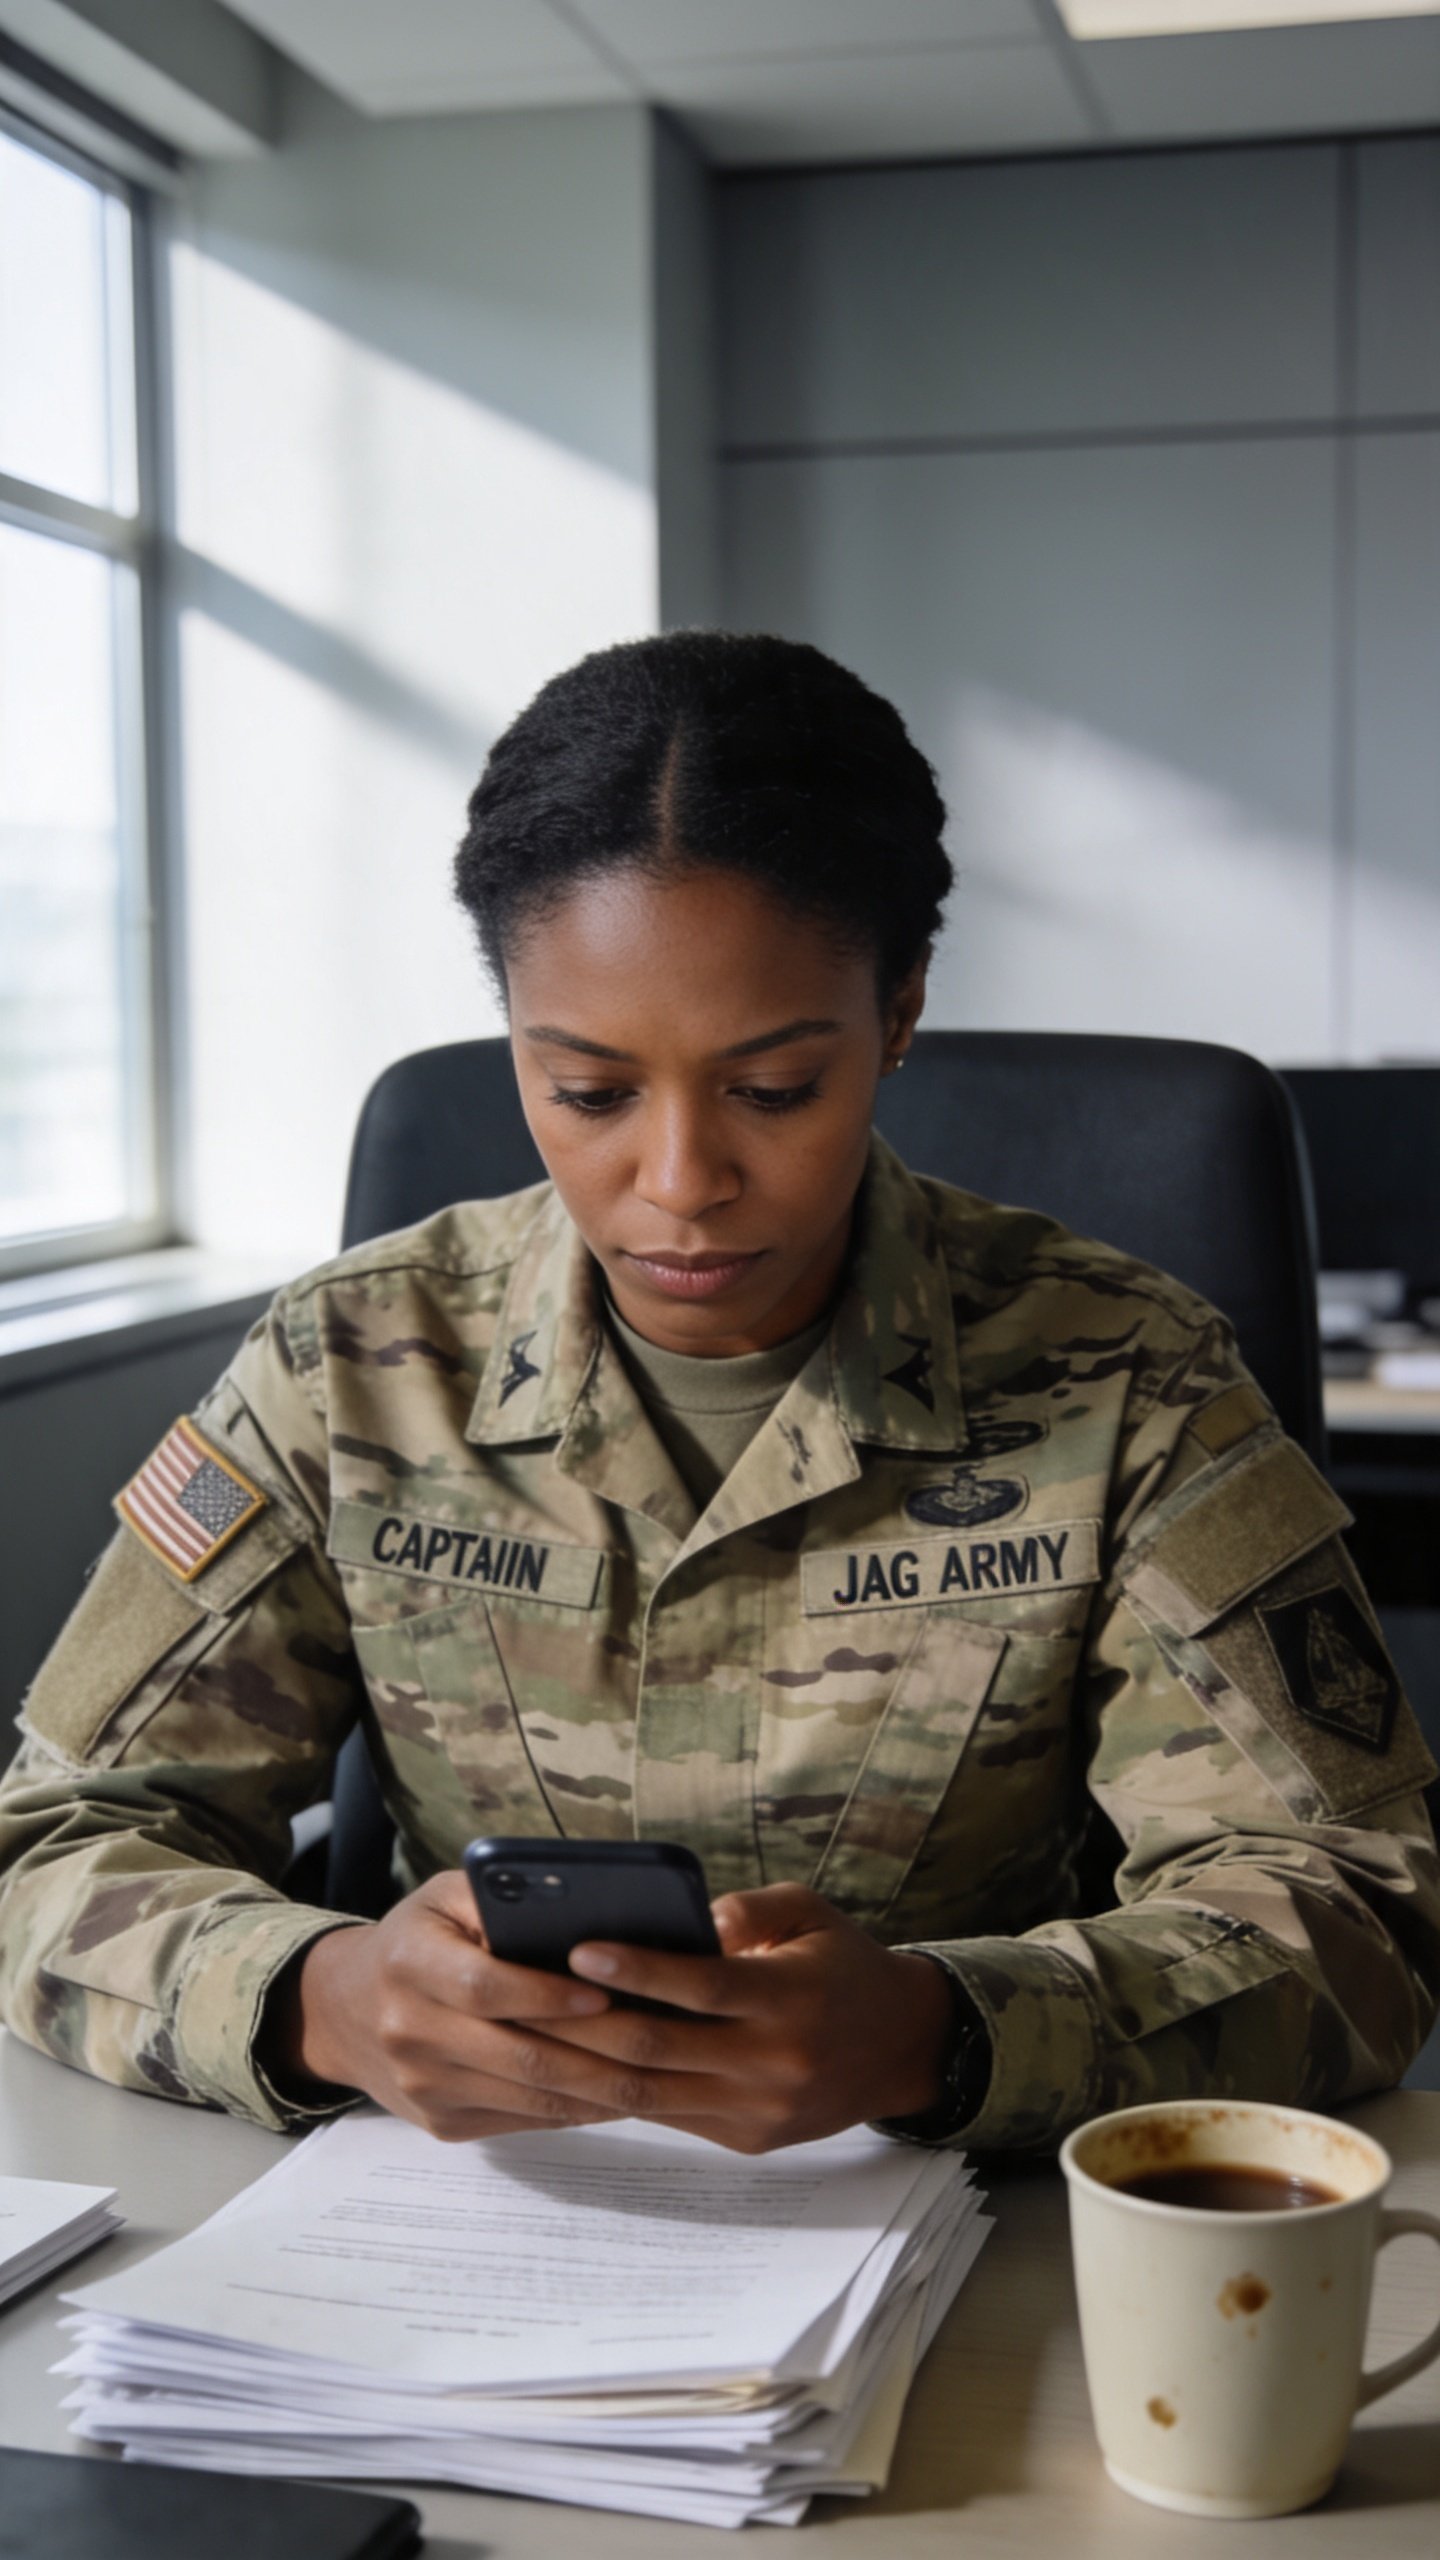
“Objection. The witness is speculating about a transaction she hasn't yet authenticated.””
My father's attorney delivered the objection with the confidence of a man who had spent years watching people retreat whenever he raised his voice.
Judge Rebecca Monroe looked over her glasses.
“Counsel, I'll allow the witness to answer questions about what she personally observed. The weight and admissibility of any document will be determined separately. Proceed carefully.””
Angela Brooks nodded.
I watched her take a breath.
She had spent eleven years keeping Mitchell Construction's books, and for two of those years, she'd lived with the consequences of refusing to sign off on questionable entries.
Now she was sitting in a courtroom where Richard Mitchell could no longer dismiss her concerns with a phone call.
My father shifted in his chair.
“Ms. Brooks,” I began, “please tell the court what your responsibilities were at Mitchell Construction.””
“I managed bookkeeping operations, reconciled accounts, reviewed invoices, and prepared financial summaries for management and outside accounting professionals.””
“Did you have access to the company's ordinary accounting records?””
“Yes, within the scope of my job.””
“Did you personally encounter transactions that you could not reconcile with the supporting documentation?””
“Yes.””
Richard leaned toward his attorney and whispered something.
The attorney shook his head slightly.
I continued.
“Did you report those discrepancies?””
“Several times.””
“And what happened when you requested supporting records?””
“Sometimes I received them. Other times, I was told to use revised classifications or wait for additional instructions.””
“Did those revised classifications resolve the discrepancies?””
“Not always.””
My father's attorney stood.
“Objection. Vague and potentially misleading.””
Judge Monroe glanced toward Angela.
“Counsel, ask a more specific question.””
I turned to the witness.
“Can you identify one example you personally documented?””
Angela opened her folder.
“An internal transfer was recorded as an ordinary project expense. The supporting invoice did not identify the service supposedly provided, and the amount didn't match the documentation I had received.””
“Did you approve the entry?””
“No. I requested clarification.””
“What happened next?””
“I received an instruction to reclassify the transfer.””
“Who gave that instruction?””
“Mr. Mitchell approved it. The instruction came through the company's internal process.””
My father abruptly sat forward.
“That is a lie.””
Judge Monroe struck the gavel once.
“Mr. Mitchell, you will have an opportunity to respond through your attorney. You will not interrupt the witness.””
His face reddened.
For the first time, I saw him realize that the courtroom had rules he couldn't rewrite.
I presented the next document, subject to the court's evidentiary requirements.
It was a transaction summary connected to one of the entries Angela had described.
The figures alone did not establish wrongdoing.
What mattered was the discrepancy between the amount recorded, the supporting documentation, and the later classification.
Angela explained how she'd identified the mismatch and where the record had originated.
Our forensic accountant then described the preliminary comparison between the internal transaction summary and the financial affidavit Richard had submitted.
The accountant was careful.
“We have identified inconsistencies that warrant further examination. We cannot yet determine the final destination of every transfer from these documents alone.””
Richard's attorney seized on that statement.
“So you cannot tell this court that my client stole money?””
“Not from these documents alone,” the accountant replied.
“You cannot say that he concealed assets?””
“I can say that certain records appear inconsistent with the financial picture presented in the affidavit. Further documentation is needed to establish the nature and ownership of the underlying interests.””
His attorney smiled as if he'd won.
Richard relaxed.
I almost smiled myself.
Because the accountant had said exactly what we needed him to say.
We weren't asking the court to convict my father of a crime based on a handful of suspicious entries.
We were asking the court to examine whether his sworn financial disclosure accurately represented his assets and liabilities.
Those were different questions.
And the evidence was beginning to show why the distinction mattered.
I returned to Angela.
“Did you ever encounter records connected to financial entities outside the United States?””
“Yes.””
“Did you personally handle every aspect of those transactions?””
“No.””
“Did you have access to all the accounts involved?””
“No.””
“Then what can you tell the court from your own knowledge?””
Angela looked toward the judge.
“I can explain the accounting entries I handled, the instructions I received, the records I reviewed, and the discrepancies I documented. I cannot claim to know what happened in accounts I never controlled.””
Judge Monroe nodded.
“That's an appropriate distinction.””
My father looked furious.
He had spent years teaching employees that loyalty meant agreeing with him.
Angela was demonstrating something different.
She could tell the truth without pretending to know more than she did.
I turned to the next tab.
“This document references an entity associated with a financial-services company in the Cayman Islands. Ms. Brooks, do you recognize the reference?””
Angela studied the page.
“Yes. I remember seeing that identifier in the company's internal records.””
“Can you tell the court who owned the entity?””
“No. I would need the underlying corporate documents to establish ownership.””
“Can you explain why you flagged the transaction?””
“The amount was inconsistent with the supporting paperwork I had available. I asked for clarification, and the issue remained unresolved in my records.””
Richard's attorney stood again.
“Your Honor, this is becoming an exercise in innuendo. The existence of an international financial relationship is not proof of misconduct.””
“I agree that the court should not draw conclusions without adequate evidence,” Judge Monroe said.
“But where the financial disclosure is disputed, relevant supporting records may be examined. Your objection is noted.””
My father leaned toward his lawyer.
“What are they doing?”” he whispered.
The lawyer didn't answer.
I heard the question anyway.
For thirty-two years, Richard had assumed he could control the story by deciding which documents other people were allowed to see.
He had forgotten that once financial records entered a proper evidentiary process, their meaning did not depend entirely on his opinion.
I lifted another page.
This one was a comparison prepared by our forensic accountant.
It showed several entries from the internal records beside corresponding figures in Richard's affidavit.
The amounts did not align neatly.
Some could have legitimate explanations.
Others lacked sufficient documentation.
The pattern was enough to justify further inquiry.
Judge Monroe studied the comparison.
“Mr. Mitchell's affidavit lists total assets below one hundred thousand dollars,” she said.
“These records appear to reference transactions and business interests that have not been adequately explained. Is that the basis of your challenge?””
“Yes, Your Honor.””
“And you are not asking me to determine today that every discrepancy represents an undisclosed asset?””
“Correct. We are asking for the supporting records necessary to determine what these transactions represent and whether the financial disclosure is complete.””
The judge looked toward my father's attorney.
“Can your client provide documentation addressing these specific entries?””
The attorney stood slowly.
“We believe the transactions can be explained, Your Honor, but we will need time to review the exhibits.””
Richard stared at him.
He had clearly expected a more decisive answer.
Judge Monroe made a note.
“Then the court will address the appropriate production requirements after hearing the remaining testimony.””
My father turned toward me.
His expression was no longer amused.
It was cold.
The same look he'd given my mother when she asked questions he didn't want to answer.
I knew that look.
As a child, I'd learned to become quiet when I saw it.
As an adult, I had learned to keep listening.
Judge Monroe called for a brief recess.
Angela stepped down from the witness stand, and our attorney accompanied her into the corridor to discuss the next stage of the proceedings.
I remained at the table with my mother.
She had barely moved during the testimony.
“Mom?””
She looked at me.
“Did you know any of this?””
She shook her head.
“I knew he kept business accounts I didn't understand. I didn't know about these entries.””
“That's why we're asking for the records.””
She looked down at her hands.
“I signed some paperwork for him years ago. Bank forms. Insurance forms. Documents he said were necessary for the company.””
My stomach tightened.
“Do you remember what they were?””
“Not exactly. He would bring them home in folders. Sometimes he'd explain them, sometimes he'd say the accountant needed my signature.””
“Did you ever sign anything authorizing someone to use your identity to open an account?””
Her eyes widened.
“No. Not that I remember.””
I didn't press her.
Memory could be imperfect, especially under stress, and we needed documents rather than assumptions.
But Angela's statement about my mother's identity had changed the direction of our investigation.
If Evelyn's identifying information had been used in a financial transaction without her informed authorization, we needed to establish exactly how.
I called our attorney over.
He listened as my mother described the paperwork she'd signed over the years.
Then he told us we'd seek the relevant applications, account-opening documents, authorizations, and transaction records through the appropriate legal process.
My mother swallowed.
“What if my name is on something I don't understand?””
“Then we'll examine the document and determine what it means,” he said.
“A signature alone doesn't answer every question about authorization, disclosure, or the purpose of a transaction.””
She nodded slowly.
For the first time, I saw fear in her expression that had nothing to do with losing money.
She was afraid that her own signature might somehow be used against her.
I took her hand.
“We're going to find out what happened.””
Across the corridor, Richard stood with Savannah.
She was speaking rapidly, gesturing with her hands.
He barely seemed to hear her.
Instead, he watched me.
When our eyes met, he walked over.
“You have no idea what you're doing,” he said quietly.
I kept my voice even.
“Then the documents should make that clear.””
He gave a humorless laugh.
“You think a few accounting records are going to destroy me?””
“No. I think the truth about those records matters.””
His jaw tightened.
“You're my daughter.””
“And she's your wife.””
For a moment, neither of us spoke.
Then he leaned closer.
“You're embarrassing this family.””
I glanced toward my mother.
“She isn't the one who filed an affidavit claiming thirty-two years of marriage produced almost nothing.””
His eyes narrowed.
“You've always been dramatic, Lauren. You get that from her.””
I could have answered with every insult he'd ever delivered.
I could have reminded him about the check, Savannah's cruelty, and the insurance cancellation.
Instead, I stepped back.
“Talk to your attorney, Dad.””
I returned to my mother.
The recess ended a few minutes later.
As we entered the courtroom, I noticed my father's attorney carrying a fresh folder.
Richard was no longer smiling.
Neither was Savannah.
Judge Monroe took her seat and announced that the court would continue examining the financial disclosures, including the disputed references to related entities.
Then she turned toward our table.
“Captain Mitchell, you indicated that there may be additional documentation relevant to the use of Mrs. Mitchell's identity. Is that correct?””
“Yes, Your Honor. We have preliminary records suggesting that her identifying information may be associated with a financial transaction. We have requested the underlying documentation and are not yet asking the court to determine whether any misuse occurred.””
“Very well. Any request for additional discovery must be properly supported and addressed through the applicable procedures.””
I nodded.
Richard stared at the judge.
For the first time, his financial affidavit was no longer being treated as the final word on his wealth.
It was a claim that had to withstand examination.
And as I opened the black binder again, I knew the next set of documents could reveal whether my mother's name had been used for something she never knowingly authorized.
May you like
My father had spent years insisting she didn't understand business.
Now the court was about to ask whether he had understood exactly what he'd signed in her name.